Product2 publishers3 min readPublished
DayOne's 2.3GW goal for 2028 is capacity it already runs or is building
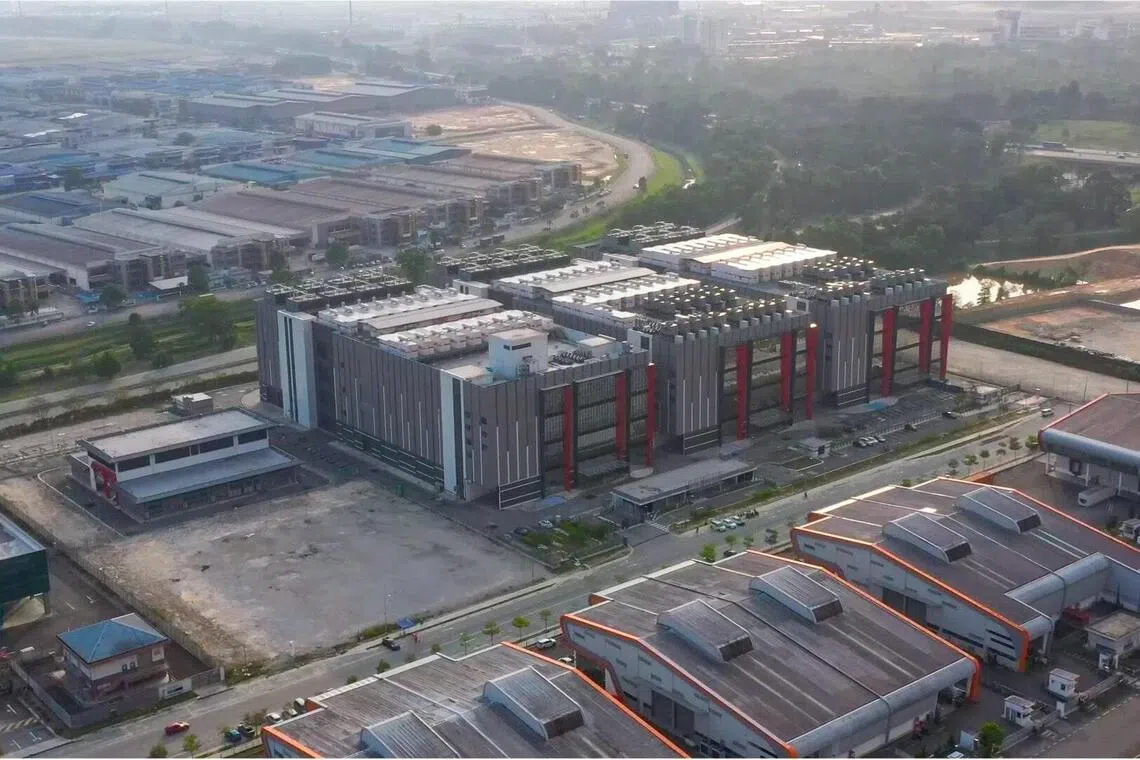
DayOne's IPO prospectus shows 962MW in service, up from 675MW in June, with 1.3GW more due by December 2028. With more than 1.5GW already booked, according to Bloomberg, buyers in Johor, Batam or Tokyo will find less of that capacity unclaimed than the 2.3GW target suggests.
The Product Desk · Product desk
Drafted by a language model from the sources cited here and checked against its claim ledger before publication. How we use AISend a correction
What happened
- First-half revenue reached $512 million in the six months to June 2026, up from about $151 million in the same period of 2025.
- DayOne runs data centers in Hong Kong, Singapore, Johor, Batam and Tokyo, and recently broke ground on new sites in Thailand and Singapore.
- Outside Asia it has announced a campus in Lahti, Finland, and has a 300MW facility in the works in Spain.
- Coatue Management and Hillhouse led a $4.5 billion Series C in June that also brought in the Indonesian Investment Authority.
- DayOne has not said how much the Nasdaq listing will raise, but Reuters and Bloomberg have reported a target of up to $5 billion at about a $20 billion valuation.
Compiled by The Product DeskSomething wrong?How this is made
Why it matters
- constraint Late arrivals are bidding for the uncontracted remainder of the build, at most about 0.8GW if bookings fall inside the target, and shared between Asian and European sites.
- decision Near-term buyers in Johor, Batam or Tokyo are likely negotiating for halls still under construction, so dated delivery terms belong in the contract from the first draft.
- exposure A tenant on a long lease is tying its capacity plan to an operator whose half-year loss grew about six-fold even as revenue rose.
A capacity planner with GPUs on order opens DayOne's prospectus wanting one answer: how many megawatts in Johor, Batam or Tokyo can still be signed for [1]. The company's headline is a plan to more than double active capacity to 2.3GW within two years [10].
The growth behind that plan is real. In-service capacity rose by about 287MW between June and September 20 [16], and the construction pipeline grew by about 200MW over the same months [18]. Add the 962MW running today to the 1.3GW being built and the total is about 2.26GW, close to the 2.3GW target [17].
The pitch implies a big new block of Asia-Pacific supply. The reported numbers show that a lot of it already has tenants. DayOne has secured more than 1.5GW of bookings since 2022 across Asia-Pacific and Europe, according to Bloomberg's report in The Straits Times [11]. Those bookings exceed in-service capacity by about 540MW, so at least that much contracted space has not been built yet [15]. If every booking sits inside the 2.3GW, no more than about 0.8GW of the target is uncontracted [13], spread over eight markets in Asia and Europe [7].
Neither report breaks the 1.3GW down by site, so how much of it is in Johor, Batam or Tokyo is unknown, as is whether the 300MW Spanish project counts toward it [4]. DayOne does already run capacity in all three of those Asian markets [3].
Revenue in the first half was about 3.4 times the year before [14]. Losses grew faster. DatacenterDynamics put the half-year net loss at $77 million against $12 million [19]. Bloomberg, citing the October 5 filing, reported $81.9 million against $13.5 million [20]. On either set of figures the loss grew about six-fold [21].
I'd count DayOne as a real candidate in markets where it already runs halls, and as a later option everywhere else [3]. The tradeoff is that bookings already outrun built capacity, so even in Johor, Batam or Tokyo the megawatts still on offer are likely to sit in the construction pipeline, with delivery dated as late as December 2028 [9][15].
Sort your own need on two axes. The first is timing: before or after the end of 2028. The second is the market: one where DayOne runs capacity now, or one where it has only broken ground or announced a campus, such as Thailand, Finland or Spain [3][4]. An early need in a live market calls for a named hall and a delivery date written into the contract. For an early need in a new market, plan on another supplier. A later need in a live market is the case for pre-leasing part of the construction pipeline. Where the need is later and the market is new, the supplier stays on the shortlist and nothing in the capacity plan depends on it.
What to watch
- An amended DayOne prospectus or roadshow material that splits the 1.3GW under construction by site, especially Johor, Batam and Tokyo.
- The next in-service figure after September 20, to test whether the June-to-September pace of about 287MW holds toward the December 2028 delivery date.
- The final size and price of the DODC listing against reported targets of up to $5 billion at about a $20 billion valuation.