Product1 publisher3 min readPublished
NextEra's $3.3bn Japan-backed tranche buys 10GW of gas, not clean firm, by 2032
Commerce and Tokyo are funding early development on two gas hubs in Texas and Pennsylvania aimed at data centers. First power is targeted for late 2028, full build for 2032.
The Product Desk · Product desk
Drafted by a language model from the sources cited here and checked against its claim ledger before publication. How we use AISend a correction
What happened
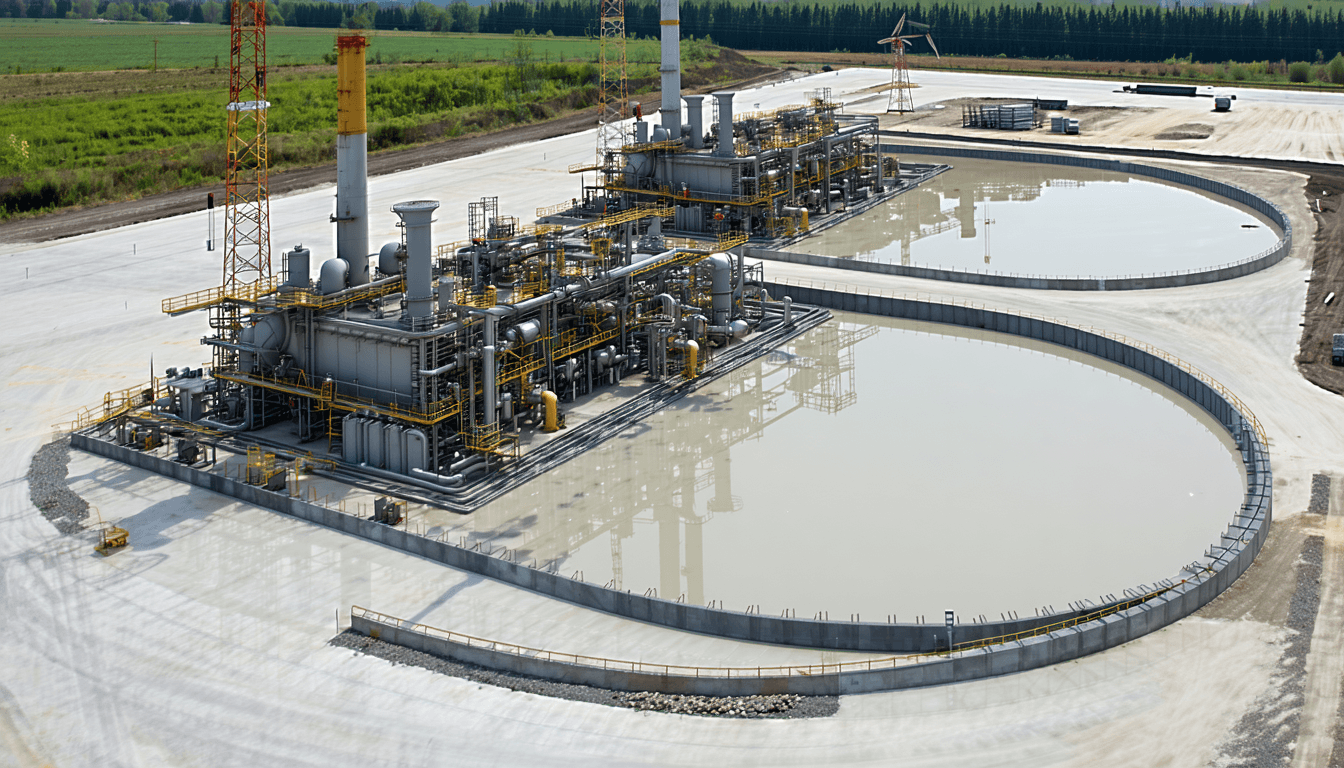
- NextEra Energy has signed agreements with the US Department of Commerce and the Government of Japan to fund up to 10GW of new natural gas generation across Texas and Pennsylvania, with the deal releasing $3.3 billion in funding for two projects.
- The new generation is expected to support data center growth across Texas and Pennsylvania; NextEra said initial resources from the projects could come online as early as the end of 2028.
- Full completion of the projects is targeted for 2032.
- The two projects are one in Texas and the $17bn South Mon project in Pennsylvania, which is expected to add 4.3GW of gas-fired capacity in the Mon Valley region.
- According to NextEra, the money will support early development costs, including down payments on turbines and long-lead equipment, and the selection of engineering, procurement, and construction contractors.
Compiled by The Product DeskSomething wrong?How this is made
Why it matters
NextEra Energy has signed agreements with the US Department of Commerce and the Government of Japan that release $3.3 billion toward up to 10GW of new natural gas generation in Texas and Pennsylvania [1]. The stated purpose is data center growth in both states, and the first resources are not expected before the end of 2028, with full completion targeted for 2032 [2][3].
Two projects sit under the tranche: one in Texas and the $17 billion South Mon project in Pennsylvania, which would add 4.3GW of gas-fired capacity in the Mon Valley [4]. That leaves up to 5.7GW attributable to the Texas site [1]. The $3.3 billion is not construction money. NextEra says it covers early development costs including down payments on turbines and long-lead equipment, plus selection of engineering, procurement and construction contractors [5]. Measured against South Mon's $17 billion cost alone, the tranche is roughly 19 percent [2]. Both projects remain subject to permitting, regulatory approval and further development and construction milestones [6].
The money comes from an unusual place for US thermal generation. According to the source, the projects were selected under Japan's $550 billion investment commitment to the US, part of a trade agreement reached in March [7]. Commerce Secretary Howard Lutnick said the investment would "commence the building of the facilities needed to bring up to 10 gigawatts of natural gas power to Texas and Pennsylvania communities" [8].
The structure matters more than the headline number. NextEra says these are two of more than 30 "energy hubs" in various stages of development, pairing new generation directly with large-load customers rather than relying on the grid [9]. On its latest earnings call the company said it is discussing 30 potential hubs, expected to reach 40 by the end of the year, and is targeting 15GW of new generation to serve large loads by 2035, with an upside case of 30GW or more [10]. This single announcement therefore accounts for about two-thirds of that 2035 target [3]. NextEra also reports approximately 21GW of large-load interest in its pipeline, 12GW of it in advanced discussions [11]. Chairman and CEO John Ketchum said the strategy reflects "more than 18 months of strategically positioning our business to capture 'bring your own generation' opportunities" [12].
On cost allocation, NextEra says the structure is designed to keep large-load customers rather than residential ratepayers covering the cost of new capacity, and that the approach is consistent with the White House Ratepayer Protection Pledge it signed in July [13]. The company frames the hubs as combining multiple power sources for different stages of data center development [14]. The capacity funded here is gas.
The operational read is straightforward. In these two markets the marginal megawatt for compute is being procured as new fossil generation with a commissioning window that stretches four years from first output to full build [4]. Anyone planning capacity that depends on it is planning past 2028.
Things to watch: whether permitting in the Mon Valley and Texas holds the 2028 date; whether the turbine down payments convert into firm delivery slots rather than options; whether the hub count actually reaches 40 by year end [10]; whether the 12GW in advanced discussions becomes signed load [11]; and whether the large-load cost separation survives contact with state regulators [13].