Georgieva says growth cannot cut US debt of more than $40 trillion fast enough
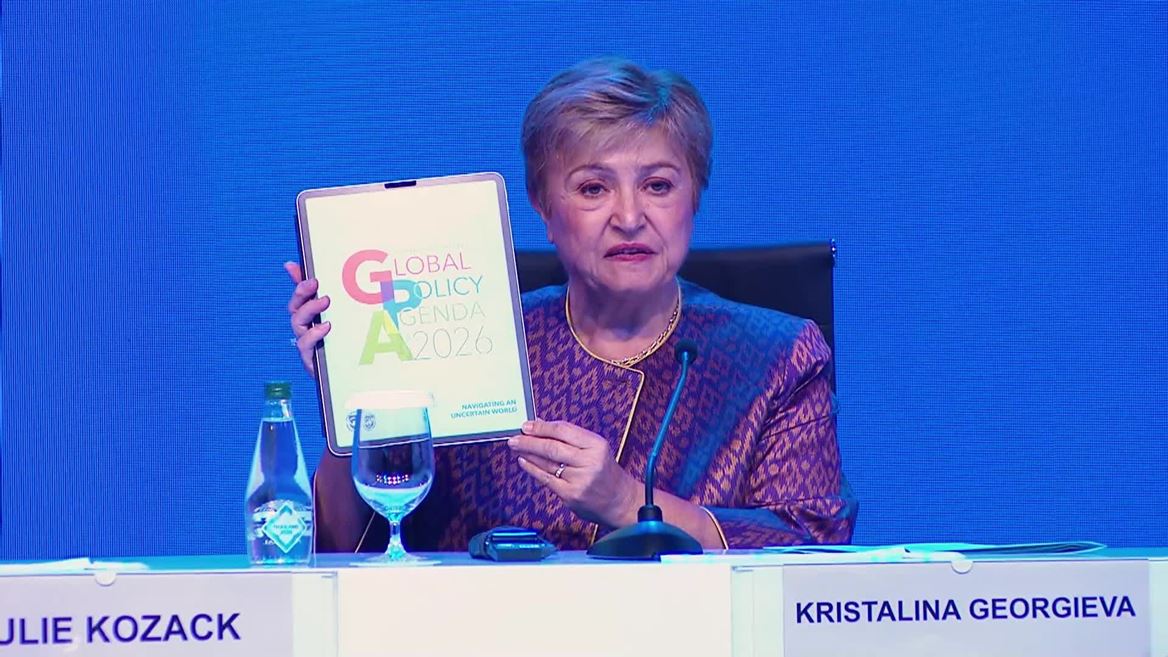
IMF chief Kristalina Georgieva said in Bangkok that growth cannot cut more than $40 trillion in US debt fast enough and that deficits must come down. Rates are already at multidecade highs, the Associated Press reported, so costlier capital is the safer planning assumption until budgets tighten.
The Board Room · Leadership desk
What happened
- Georgieva said Treasury Secretary Scott Bessent and other US leaders recognize that the federal deficit and national debt have grown too high.
- The Associated Press report states that rising bond yields, reflecting higher premiums for greater risks, have been disrupting financial markets.
- The IMF's latest Fiscal Monitor says interest payments in the world's poorest countries have reached historic highs relative to revenue.
- Alexander De Croo, administrator of the UN Development Programme, noted that the median developing country pays three times more on interest repayments than developed countries.
Why it matters
- decision A financing plan that assumes relief this quarter depends on a policy response Valdes says is largely absent in many countries. If it does not arrive, next quarter's refinancing meets the same elevated rates.
- constraint Rate relief is only partly in finance ministers' hands. The wire report ties inflation partly to energy costs from the Iran war and does not say how much of the rate level that explains, so we do not know yet how far tighter budgets alone would bring borrowing costs down.
- exposure Government customers and receivables in poorer countries carry repayment risk, because those governments are already choosing between supporting vulnerable people and paying lenders.
Georgieva's argument is about pace, and she grants that growth helps. "At the fund, we believe that, growth, of course, helps, but it cannot deliver fast enough the necessary adjustments," she said on Wednesday at the autumn meeting of the IMF and World Bank in Bangkok [1][5].
The remedy she offered is short. "There is no magic," she said, noting some other measures would be needed. "You have to go in a direction of tightening ... bringing the deficit down." [6] The path has been uneven. Efforts at what Georgieva and other experts call "fiscal consolidation" have suffered setbacks from heavy spending during the COVID-19 pandemic and since [15].
The IMF's own fiscal director describes the same gap from the other side. "Fiscal risks are rising, and a proper reaction is largely absent in many countries," said Rodrigo Valdes, director of the IMF's Fiscal Affairs Department [8]. By his account, the response the fund wants has not arrived in many countries.
In the wire report, the remarks quoted from Georgieva address growth and tightening. The sentence on bond yields is the wire's own [4]. In our view, rates reprice faster than budgets move, so costlier capital arrives before any tightening does. That separates this quarter's planning, which has to use today's rates, from the multi-year question of whether budgets tighten.
The spillover is the part of the argument aimed outside the US. "And in major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world," Valdes said [9]. U.K. Foreign Secretary Ed Miliband, speaking at an event on the sidelines of the meetings, put the cost in similar terms: "The Global South is paying the price for rising interest rates in wealthier countries" [12]. His proposed remedy came in the same remarks. "We need a new deal on debt, a deal that supports countries to repay over longer time horizons and, crucially, refinancing with better rates to give developing countries precious fiscal space," he said [14].
What to watch
- Whether the IMF, the US Treasury or any other government attaches a deficit target and a timetable to the call for tightening.
- Whether energy costs tied to the Iran war ease, since the AP report links them to the inflation behind high rates.
- Whether lenders respond to the longer repayment terms and cheaper refinancing that Miliband asked for.
Clarity's read
What the record supports and how the coverage leans. The claims behind it follow.
Reality
- Evidence55
- Adoption
- Insufficient
- Hype gap+5
- Incentives
- Insufficient
- Confidence55
Claim ledger
Ranked by verification strength, evidence, and original report placement.
- [1]
IMF Managing Director Kristalina Georgieva said on Wednesday, at the autumn meeting of the IMF and World Bank in Bangkok, that the US and other wealthy nations need to urgently tackle mounting global debt levels.
- [2]
Georgieva said US Treasury Secretary Scott Bessent and other US leaders recognize that the federal deficit and national debt have grown too high.
- [3]
Georgieva said that just trying to grow the US economy out of its more than $40 trillion in national debt would not suffice.
- [4]
Rising bond yields, reflecting the higher premiums associated with greater risks, have been disrupting financial markets, the Associated Press report states in its own voice.
- [5]
"At the fund, we believe that, growth, of course, helps, but it cannot deliver fast enough the necessary adjustments," Georgieva said.
- [6]
"There is no magic," Georgieva said, noting some other measures would be needed. "You have to go in a direction of tightening ... bringing the deficit down."
- [7]
Rising debt levels and global inflation, partly resulting from high energy costs due to the Iran war, have pushed interest rates to multidecade highs.
- [8]
"Fiscal risks are rising, and a proper reaction is largely absent in many countries," said Rodrigo Valdes, director of the IMF's Fiscal Affairs Department.
- [9]
"And in major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world," Valdes said.
- [10]
The IMF's latest Fiscal Monitor says that among the world's poorest countries, interest payments have reached historic highs relative to revenue.
- [11]
Poorer countries are being forced to make hard choices between supporting their most vulnerable people and meeting their debt repayment obligations.
- [12]
"The Global South is paying the price for rising interest rates in wealthier countries," said U.K. Foreign Secretary Ed Miliband at an event on the sidelines of the IMF meetings.
- [13]
Alexander De Croo, former Belgian prime minister and administrator of the United Nations Development Programme, noted that the median developing country pays three times more on its interest repayments than developed countries.
- [14]
"We need a new deal on debt, a deal that supports countries to repay over longer time horizons and, crucially, refinancing with better rates to give developing countries precious fiscal space," Miliband said.
- [15]
Efforts to bring debt under control with what Georgieva and other experts call "fiscal consolidation" have suffered setbacks from heavy spending during the COVID-19 pandemic and since.
Get this ledger inside ChatGPT. Ask about any of our stories and the answer brings its figure, each claim’s verdict and the sources. Free, no account.
Sources
2 independent publishers whose own reporting we read for this story.
- abcnews.comIMF chief urges wealthy nations to rein in debt to ease global economic pressure
1 article · October 14, 2026
- scmp.comIMF head urges US and rich nations to rein in deficits as global debt soars
1 article · October 14, 2026
Topics and entities
Follow any of these and your For You feed starts watching them — no settings page required.