Invest1 publisher2 min readPublished
SB Energy postpones $50bn listing as investors balk at 360x revenue multiple
SoftBank's data centre arm filed on September 1 to raise $5bn to $7bn on Nasdaq, and the price under discussion works out at about 180 times an annualized half-year revenue of $139m against $439bn of contracted backlog.
The Investor · Invest desk
What happened
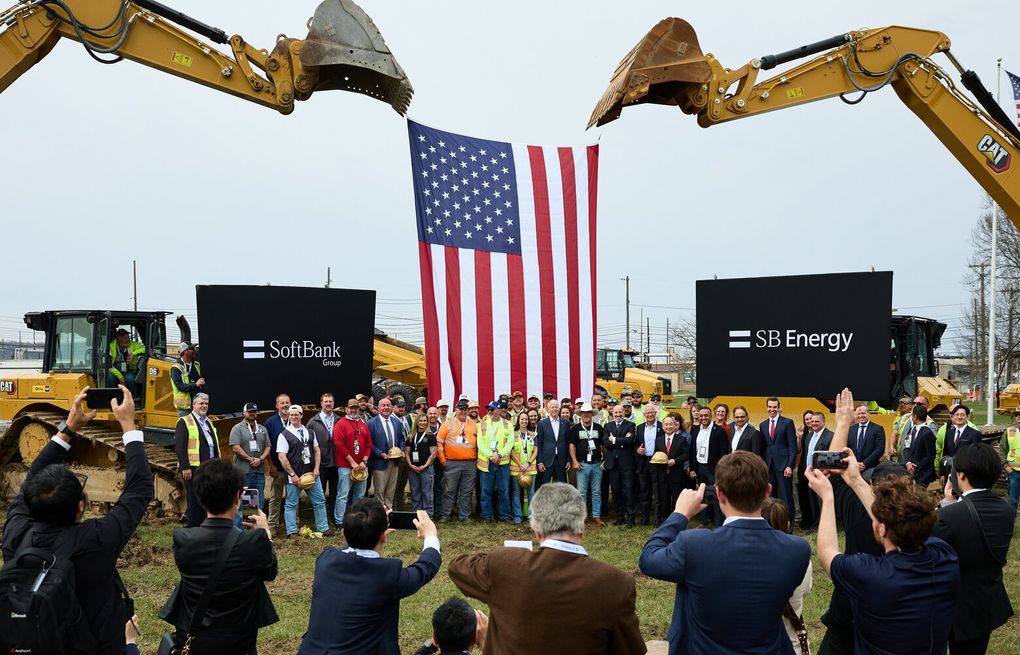
- SB Energy has moved its planned Nasdaq listing from September to at least mid-to-late October, with cryptobriefing.com reporting that prospective investors are not accepting the roughly $50bn valuation.
- The company filed its S-1 with the SEC on September 1 to list under the ticker SBE, seeking $5bn to $7bn while SoftBank stays majority owner.
- Forward capital expenditure is projected above $170bn, and Nvidia has committed $1.5bn plus up to $105bn in guarantees for a data center project in Ohio.
Compiled by The InvestorSomething wrong?How this is made
Why it matters
- constraint Equity is not what pays for this build, so the bulk of the $170bn has to be found in debt and vendor guarantees whatever price the October book clears at.
- exposure Anyone buying SBE stock is taking a multi-year credit view on OpenAI's ability to pay lease instalments, since it is the dominant tenant behind the backlog.
- decision The syndicate now has to choose between trimming the ask and waiting for demand to arrive at the old number, with a few weeks of marketing to decide it.
- precedent Whatever SBE eventually prices at becomes the reference point for the next contracted-capacity developer that comes to market with gigawatts signed and nothing yet running.
The same two numbers give two different multiples. Cryptobriefing reported that SB Energy is asking investors to value it at roughly 360 times its annualized revenue run rate [9]. Fifty billion dollars divided by the $139m the company booked in the first half of 2026 is 360 [8][1]; double that half year into a $278m run rate and the multiple is 180 [2]. Both are steep for a company that has not switched on a data centre [3].
The offering funds a small corner of the build. The S-1 seeks $5bn to $7bn [5] against projected capital expenditure above $170bn [11], which works out at 2.9 to 4.1 per cent of the programme [3]. At $50bn, that sale is 10 to 14 per cent of the company [2][4]. Nvidia's commitment of $1.5bn plus up to $105bn in guarantees for an Ohio project [14] is worth about twice the entire equity value now being argued over [5].
The backlog is the asset being sold. About $439bn of contracted backlog sits on 8.8 GW of contracted capacity [6][7], or roughly $49.9bn per gigawatt [6], against about $19.3bn of projected capex per gigawatt [7]. Both are gross figures, and the revenue side accrues over long-term leases [6]. OpenAI is the primary source of that contracted revenue [12], and its own IPO timing is unsettled [13].
OpenAI turns up on both sides of SoftBank's plan: it anchors the SB Energy lease book [12] and is a partner in the $100bn Stargate commitment alongside Oracle and others [15].
Then there is the loss. SB Energy posted a $3.21bn net loss over the same six months, which cryptobriefing attributes primarily to its legacy renewable energy operations [10], and that loss is 23 times the half's revenue [8].
One rescheduled book is thin evidence that AI infrastructure issuance in general is being marked down. The report does not name an investor, and neither SB Energy nor SoftBank is quoted in it [17]. What it does say is that the move to mid-to-late October gives the bankers a few extra weeks to court investors, potentially at a revised valuation [16][1].
I would expect the price to move before the calendar does again, because the only variable the syndicate controls at 180 times revenue is the number in front of it. The counter-case is respectable: a buyer is underwriting 8.8 GW of contracted leases with an anchor tenant and a chipmaker's guarantees behind them [7][12][14], and a few weeks of delay in a $5bn-plus deal is ordinary book management. If SBE prints in October at or above $50bn and takes the full $7bn [5], this reading was wrong.
What to watch
- An amended S-1 that changes the deal size or the indicated range, which would show where demand actually sits.