Product1 publisher3 min readPublished
Dairy's $10.4bn Protein Claim Is Now A Legal Asset, Not A Formulation Choice
Protein call-outs are about a tenth of the US dairy market but most of its growth, and Danone and Chobani are in court over those claims. Substantiation is the new constraint.
The Product Desk · Product desk
Drafted by a language model from the sources cited here and checked against its claim ledger before publication. How we use AISend a correction
What happened
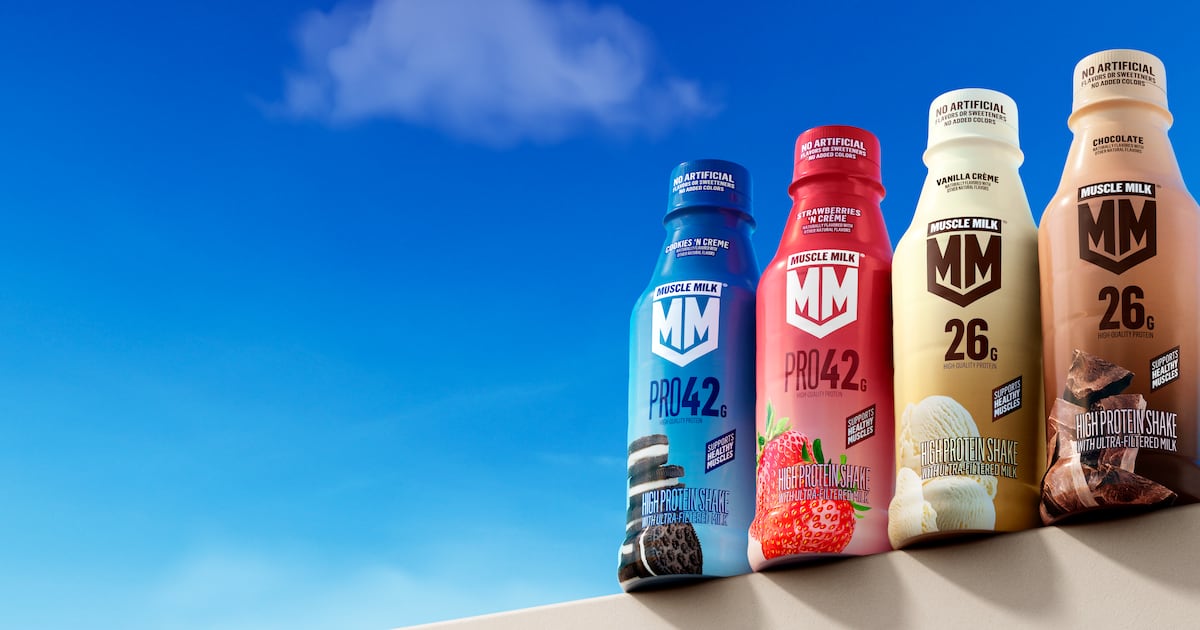
- Dairy products carrying protein claims represent a $10.4bn segment within the $104bn US dairy market, according to Circana retail data.
- Over the past year, dairy products with protein call-outs grew 13.7% in value and 7.5% in volume, compared with 2.0% and 0.3% respectively for the broader dairy segment.
- Danone and Chobani have clashed in court over protein claims.
- dairyreporter.com states the Danone-Chobani court clash highlights that the battle for market share increasingly comes down to how much protein a product can credibly promise.
- Protein yogurt sales climbed 23.2% in value and 16.8% in volume, ahead of conventional yogurt at 12.2% and 7.3% respectively.
Compiled by The Product DeskSomething wrong?How this is made
Why it matters
Circana retail data puts dairy products carrying protein claims at $10.4bn inside a $104bn US dairy market, and Danone and Chobani have gone to court over protein claims [1][3]. Those two facts belong together: once a line of front-of-pack copy is attached to roughly a tenth of a category and most of its growth, the claim stops being marketing and becomes an asset someone will litigate [11].
The growth split is the reason. Over the past year, dairy with protein call-outs grew 13.7% in value and 7.5% in volume, against 2.0% and 0.3% for the broader category [2]. That is about 6.9 times the value growth and roughly 25 times the volume growth [12]. Run it through the base and the protein-claimed segment accounts for something like 61% of the dollar growth of the entire US dairy market while representing about 10% of its sales [14][11].
The price story is more interesting than the volume story. Protein-claimed dairy shows a 6.2 point gap between value and volume growth, against 1.7 points for dairy overall [13]. Shoppers are paying more per unit specifically where the claim appears. High-protein milk is the cleanest case: conventional dairy milk was largely flat, while high-protein milk grew 7.7% in value on just 1.2% in volume, a 6.5 point gap that is almost entirely price and mix [7][16]. Protein yogurt grew 23.2% in value and 16.8% in volume, ahead of conventional yogurt at 12.2% and 7.3% [5], with a 6.4 point value-volume gap against 4.9 points for the conventional segment [17].
Cottage cheese is the counter-example worth pinning to the wall. Protein-claimed cottage cheese grew 18.1% in value and 14.6% in volume, but the category as a whole grew 16.5% and 12.0% [6]. The claim adds 1.6 points of value growth and 2.6 points of volume growth over a category that was already moving [15]. In a product that is inherently high in protein, the label earns very little incremental premium. The pricing power sits where the claim is doing work the base product cannot do on its own.
Which is where substantiation bites. Formulation is not the hard part; ultrafiltration and protein isolates are available to anyone with a co-packer. What is scarce is the ability to defend a number. Brands including Fairlife and Darigold Fit have built portfolios stacking protein with lactose-free, lower sugar and ultrafiltered claims [8], and yogurt lines including Oikos Pro, Oikos Triple Zero, Chobani Protein, Yoplait Protein, Light & Fit and siggi's are pushing protein per pack alongside reduced or no added sugar [9]. Every claim added to that stack is another number a competitor can test in a lab and put in front of a judge. The Danone and Chobani dispute, as dairyreporter.com frames it, shows the fight for share now turning on how much protein a product can credibly promise [4].
Watch three things. First, whether the Danone and Chobani litigation produces anything resembling a working standard for what a protein claim must prove, because that becomes the specification everyone else designs to. Second, whether the cottage cheese pattern spreads: if claim-driven premiums compress in categories that are naturally protein-dense, the 6.2 point price gap narrows and the segment's economics change [15][13]. Third, whether the same claim scrutiny follows the trend into Europe, Australia and parts of Asia, where manufacturers are already investing in high-protein dairy [10].