Invest1 publisher3 min readPublished
One $400M round held up crypto's July: 41 rounds and 140 investors, both at lows
Venture dollars slipped only 6.8% from June, but round count fell 28% to a 12-month low and unique institutional investors fell 31%. Excluding Crypto.com's cheque, investment was down 34%.
The Investor · Invest desk
Drafted by a language model from the sources cited here and checked against its claim ledger before publication. How we use AISend a correction
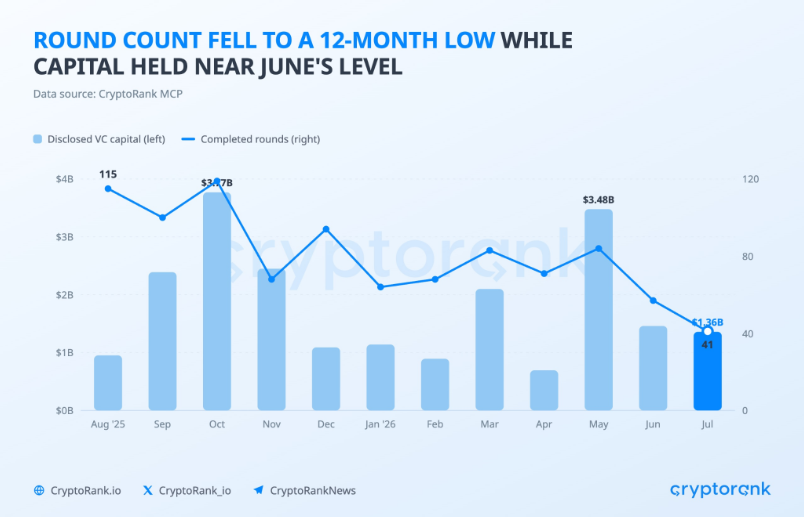
What happened
- Crypto companies raised $1.36B across 41 VC rounds in July; investment slipped 6.8% from June.
- Crypto.com's $400M strategic round supplied 29.4% of monthly VC investment; excluding it, investment would have been $960M, down 34.2% from June.
- Round count fell 28.1% to 41, the lowest total in the 12-month window.
- The 41 rounds were 63.1% below the 111 rounds completed in July 2025.
- Mean round size rose from $25.6M in June to $33.2M in July; without Crypto.com's $400M round, July was $960M across 40 rounds, or $24M per round.
Compiled by The InvestorSomething wrong?How this is made
Why it matters
Crypto companies raised $1.36B across 41 venture rounds in July, a decline of just 6.8% from June, according to Cryptopolitan's reading of CryptoRank data [1]. The headline number survived because Crypto.com's $400M strategic round supplied 29.4% of it; without that single transaction, investment was $960M, down 34.2% from June [2].
The round count is the cleaner signal, and it is not ambiguous. At 41, July was the lowest month in the trailing 12, down 28.1% from June and 63.1% below the 111 rounds completed in July 2025 [3][4]. June, by the source's own arithmetic, closed 57 rounds [1]. Mean round size rose from $25.6M to $33.2M, which reads as strength until you remove the largest cheque: 40 rounds and $960M works out to $24M each, slightly below June's average [5][2].
Concentration did the rest of the work. The ten largest rounds took 85% of venture investment [6], which leaves roughly $204M for the other 31 deals, about $6.6M apiece [3]. Later-stage investment was the one expanding group, up 94.4% to $661M from $340M in June, but Augustus, Prime Intellect and Gauntlet supplied $435M of that, or 65.8% [7]. Strategic investment fell 8.8% to $542M, seed and pre-seed fell about 18% to $100M, and the two large groups together took 88.5% of the month [8][9]. Early-stage financing was roughly 7% of disclosed venture dollars [4].
The investor side moved with the deal pipeline rather than against it. CryptoRank counted 140 unique institutional investors, down 30.7% from 202 in June and 66.1% from 413 in July 2024, the lowest observation in its corrected 25-month series [10]. Sixty-two investors left the tape in a single month [11]. Notably, investors per completed round barely changed, at about 3.4 in July against 3.5 in June [5], so syndicates are not thinning; there are simply far fewer of them to join.
Category data repeats the pattern. Exchanges led with $543M across seven rounds, of which Crypto.com was 73.7% [12]. AI led on activity with eight rounds, but Prime Intellect and Venice AI accounted for $195M of the category's $232M, or 84.1% [13]. Payments took $244M across four rounds [14]. Across all transaction types, CryptoRank identified $2.13B in publicly disclosed investment: venture at 63.9%, Strategy's $466.7M post-IPO raise at 21.9%, and Alpaca's $300M debt facility at 14.1% [15]. Seventeen acquisitions closed with no publicly disclosed value, so M&A added transactions and no measurable total [16].
For operators, the practical read is that large cheques remain available to a short list of companies while the number of firms writing any cheque at all is contracting. A market where the top ten deals are 85% of the money and the median participant sees $6.6M is not a market that has stabilised; it is one that has narrowed [6][3].
Watch three series next month. Whether unique investors recover toward June's 202 or hold near 140, which distinguishes a reporting lag from a structural exit [10]. Whether round count climbs off 41, since dollar totals can be manufactured by one strategic investor and counts cannot [3]. And whether seed and pre-seed clears the $100M mark, because that line, not the headline, tells you what gets funded in 2028 [9].