Invest1 publisher3 min readPublished
Crusoe's Series F values a $140 billion backlog at 22 cents on the dollar
Atreides Management, Mubadala Capital and Valor Equity Partners co-led an initial close of $3.9 billion at a $30.9 billion post-money valuation. One of Crusoe's six contracted gigawatts is running today.
The Investor · Invest desk
What happened
- Crusoe said on September 17 that it had completed the initial closing of an anticipated $3.9 billion Series F, a round the company described as oversubscribed.
- NVIDIA, GIC, the Qatar Investment Authority, Founders Fund, Radical Ventures and TPG joined the round alongside the three co-leads.
- Crusoe Managed Inference, launched late last year, has contracted more than $100 million of ARR, and Crusoe Cloud bookings are up more than 20 times year over year.
Compiled by The InvestorSomething wrong?How this is made
Why it matters
- exposure Buyers at $30.9 billion are underwriting counterparty quality they cannot see. The company described its customers by category, with no names and no contract lengths.
- constraint At roughly $780 million of new equity per undelivered gigawatt, the pace of the build depends on financing Crusoe has not announced.
- precedent A chip vendor taking equity in a cloud it also certifies makes supplier-funded demand an ordinary term in AI infrastructure rounds. Other clouds will ask for it.
- decision Calling this an initial closing leaves later investors choosing between paying the same mark now and waiting to see delivered capacity catch up with contracted capacity.
Divide the two largest figures in the announcement and you get the price. The $30.9 billion post-money valuation sits against more than $140 billion of total contracted value [1][4], which works out to about 22 cents of equity for every dollar of contracted revenue [3]. Spread over the more than 6 gigawatts of gross contracted capacity, that backlog is roughly $23 billion a gigawatt [5][4]. Crusoe kept contract tenors, counterparty names and the debt behind the build out of the announcement [13].
The dilution is small for the money. Putting $3.9 billion into a $30.9 billion post-money implies a $27.0 billion pre-money and about 12.6 percent of the company [1][2]. Crusoe called this the initial closing of an anticipated round [1], so the total can rise at the same mark.
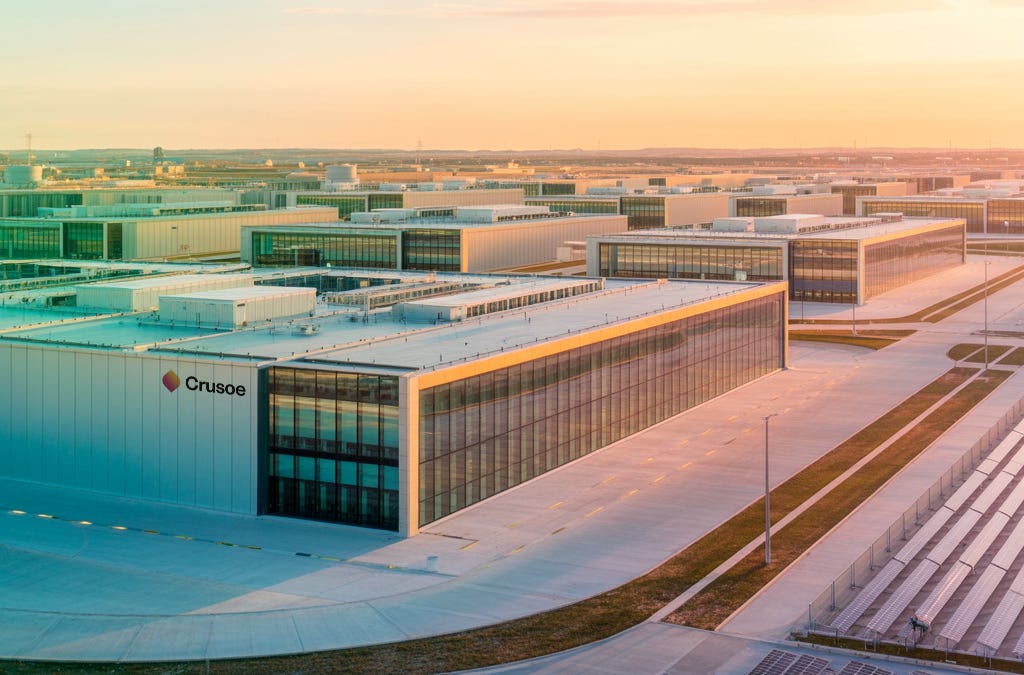
One gigawatt is delivered and operational against more than six contracted [5], so at least five remain, and $3.9 billion is about $780 million per undelivered gigawatt [5]. The company says the capital will scale existing programs and fund its own AI factories, from large-scale campuses to modular Crusoe Spark units [14]. Its power plan is in-house plant development paired with partnerships across grid, battery, nuclear, thermal and renewable supply [15].
Gavin Baker, managing partner and CIO of co-lead Atreides Management, said "As AI grows, the economics flow to the lowest-cost producer of intelligence." [2][9] Chase Lochmiller, Crusoe's co-founder and chief executive, said "Getting there means controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction." [8]
NVIDIA is among the investors [3], and Crusoe lists itself as an NVIDIA Exemplar Cloud [10]. The chip supplier now holds equity in a customer whose 6 gigawatts of contracted capacity is, among other things, a forecast of chip demand. Series F buyers own a piece of that loop too.
If the backlog converts near its contracted values, 22 cents on the dollar will look like a discount and the next round prices above $30.9 billion. The second reading is that a meaningful share of it hangs on capacity that lands late or gets renegotiated, in which case the asset base an investor is underwriting is the one gigawatt running now, about a sixth of what is contracted [6]. A third: data-centre debt prices wider than the plan assumes, and this equity funds the gap while that resets. I lean to the second, because the only recurring revenue figure disclosed is the $100 million of contracted ARR on Managed Inference, which is 0.07 percent of the total contracted value [7][7], and because the more-than-20x growth in Crusoe Cloud bookings is a rate given without a base [6].
Tenor and counterparties would settle it. If most of the $140 billion is take-or-pay with investment-grade buyers over ten years or more, $30.9 billion is too low and Atreides, Mubadala Capital and Valor bought cheap [1][2][4].
What to watch
- Whether subsequent closings of the anticipated round come in at the same $30.9 billion post-money mark or reprice.
- Any debt or project financing package announced against the five-plus gigawatts still to be built.
- The next update to the 1 GW delivered-and-operational figure, which is the only capacity number an investor can currently verify as earning.