Invest1 publisher2 min readPublished
Crusoe's $3.9bn round prices a contract book that runs five gigawatts ahead of delivery
The Series F closed at a $30.9bn post-money valuation on one operating gigawatt and $140bn of contracted value spread across six. Turning the other five gigawatts into cash is what the new money bought.
The Investor · Invest desk
What happened
- Crusoe announced the initial closing of a $3.9 billion Series F at a $30.9 billion post-money valuation on September 17, co-led by Atreides Management, Mubadala Capital and Valor Equity Partners.
- The company reports more than $140 billion of total contracted value across a platform selling to AI natives, hyperscalers, frontier model labs and enterprises.
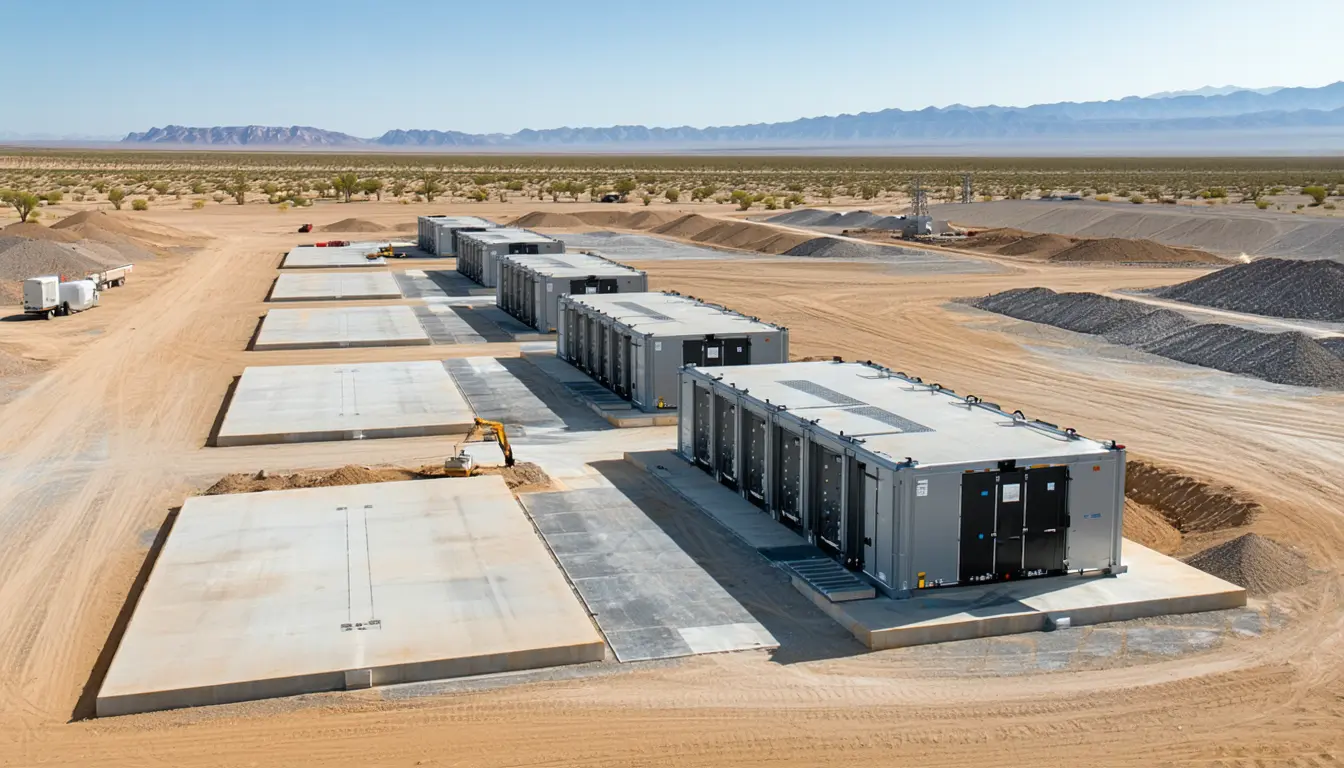
- Gross contracted capacity is over 6GW across data centers and cloud, of which 1GW is delivered and operational today.
- CrusoeManaged Inference, launched late last year, has contracted over $100 million in ARR, and Crusoe Cloud bookings are up more than 20x year over year to date.
- NVIDIA, GIC, the Qatar Investment Authority, Founders Fund, Radical Ventures and TPG all put money into the round alongside the three co-leads.
Compiled by The InvestorSomething wrong?How this is made
Why it matters
- constraint Equity of this size covers a thin slice of a five-gigawatt build, so the delivery schedule now depends on what lenders and project finance markets will fund at what coupon.
- exposure Crossover managers including Fidelity, T. Rowe Price and Baillie Gifford now carry a private power-to-cloud developer in funds that retail investors hold, and the mark moves with capacity that is not yet built.
- decision NVIDIA is now a shareholder in a cloud it also certifies. Its allocation choices among neoclouds come with an ownership interest attached.
- precedent Pricing a private developer at roughly a fifth of its contracted value hands the next AI infrastructure raise a comparable to argue from.
About $23.3bn of contracted value sits behind each contracted gigawatt [15]. Five of the six gigawatts are unbuilt [16], and the new equity works out at roughly $780m per unbuilt gigawatt [17]. The rest has to come from debt, project finance, customer prepayments or a later round. Crusoe says the money will scale existing programs and support the buildout of its own AI factories, from large vertically integrated campuses to modular Spark units [11].
At $30.9bn post-money the equity is priced at about 22% of the contract book behind it [18], and the $3.9bn bought roughly 12.6% of the company off a $27bn pre-money [19]. The contracted inference ARR in the announcement comes to about 0.07% of that contract book [20]. Crusoe did not disclose group revenue.
Gavin Baker, whose Atreides Management co-led the round [2], said "As AI grows, the economics flow to the lowest-cost producer of intelligence." [10] Chase Lochmiller, co-founder and chief executive, said "Getting there means controlling the infrastructure from electrons to tokens, and we're grateful to have investors who share that conviction." [9] Both are claims about cost structure. The cost claim rests on originating and managing power at the source, with in-house power plant development paired with grid, battery, nuclear, thermal and renewable partners [12].
The release puts the advantage in power [12]. NVIDIA, which designates Crusoe an Exemplar Cloud [14], is also an investor in the round [3]. The chip supplier and the power developer now sit on the same cap table.
Conversion decides this one. If the five unbuilt gigawatts land on schedule and the contracts price above the delivered cost of power, shells and hardware, then $23.3bn per contracted gigawatt [15] makes $30.9bn [1] look like a discount. If delivery slips, or counterparties can walk, the $140bn [4] is an option book and the equity was priced against capacity that is not yet operating. I lean to the first case, on the strength of the gigawatt already running [5] and a syndicate that includes Mubadala Capital, GIC and the Qatar Investment Authority [2][3]. Any of them can fund the next five gigawatts if lenders hesitate.
What to watch
- A second closing: this was an initial close, so the final round size and whether $30.9bn holds are both open.
- Any disclosure separating delivered revenue from the $140bn of contracted value, which would give a conversion rate to test.
- The debt or project finance package behind the five unbuilt gigawatts, and the cost of capital attached to it.