Invest1 publisher3 min readPublished
A 12.25% cap makes credit unions sell down their biggest property loans
Credit unions held $187.1 billion of commercial loans secured by real estate at June 30, up 36% in two years. Citadel marketed positions in its record $50 million Philadelphia office loan to other financial institutions.
The Investor · Invest desk
What happened
- Commercial loans secured by real estate on credit union books reached $187.1 billion at June 30, up 36% from the same date in 2023, according to NCUA statistics released last week.
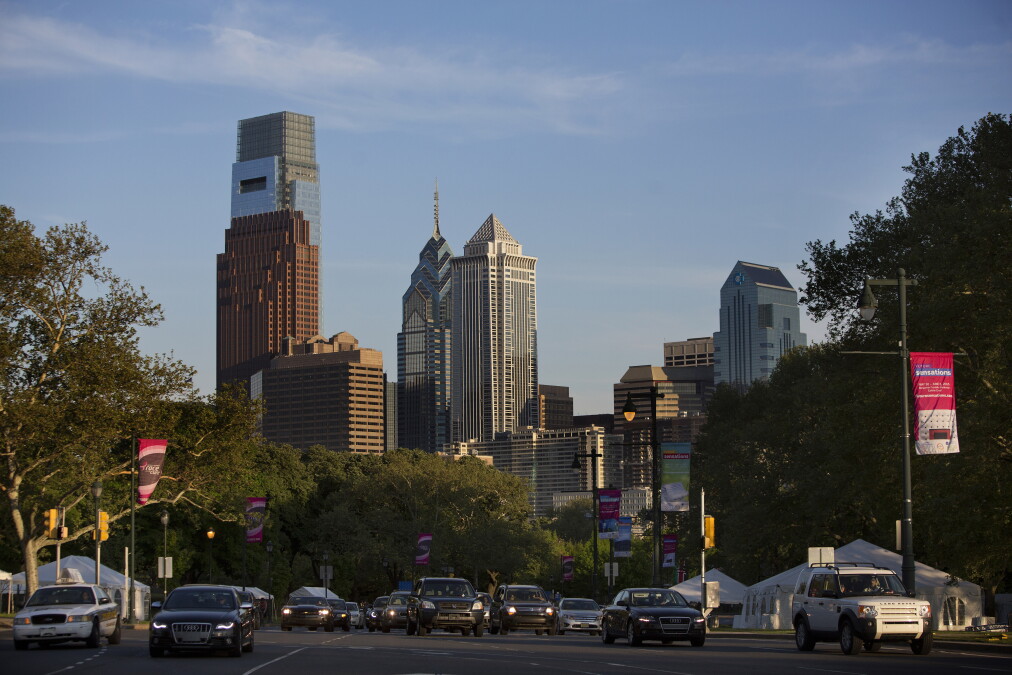
- Citadel Credit Union closed a $50 million loan on a 29-story office tower in Philadelphia's Center City, the largest business loan in its 88-year history.
- Bryan Moore, St. Mary's commercial lending chief, said the credit union's largest recent transactions are "$5 million or $6 million deals."
Compiled by The InvestorSomething wrong?How this is made
Why it matters
- constraint A credit union's commercial book can only outrun the statutory ceiling if the loans move off its balance sheet. That makes the buyer list for participations, not credit appetite, the limit on how large a deal it can lead.
- capability Recruiting commercial lenders out of community banks gives a credit union bank-scale underwriting without years of building it, and it let Citadel source and lead the Philadelphia deal instead of buying into someone else's.
- exposure Whoever takes a position in the Philadelphia loan is buying office risk underwritten by an institution relatively new to commercial lending.
- contradiction American Banker reports that few credit unions have closed anything as large as Citadel's loan, so a banker deciding whether he is losing deals has to read the 36% aggregate and the large-ticket count as two separate questions.
A credit union's commercial loans are capped at roughly 12.25% of total assets [2]. Each dollar on the book therefore needs about $8.16 of assets behind it [6]. Applied to the industry total, the $187.1 billion reported at June 30 [1] puts a floor of about $1.53 trillion under combined credit union assets [5]. A floor, not an estimate, because the real-estate line is only part of the commercial book the cap covers [2].
The 36% growth figure covers two years. Working back from June, the mid-2023 base was about $137.6 billion [1], so the sector added roughly $49.5 billion [2], about $2.06 billion a month [3]. Citadel's loan, the largest business loan in the Exton, Pennsylvania credit union's 88 years [3], is a tenth of one percent of that addition [4].
Most of the growth came in smaller pieces. Built Technologies, whose construction lending platform counts more than 40 credit unions as clients, up from a handful a few years ago [6], told American Banker that "Credit unions now have 16 active CRE loans over $10 million on the platform, up from just three in 2023" [7]. Sixteen loans at $10 million or more is at least $160 million across that whole platform [8]. At St. Mary's Credit Union in Marlborough, Massachusetts, which holds about $1 billion in assets [9], Bryan Moore said of the recent records: "We're talking $5 million or $6 million deals" [11]. Citadel's single loan is eight to ten times that [9].
St. Mary's held $64.5 million of commercial loans secured by real estate at June 30, up about 20% from the end of 2024, according to NCUA data [12]. On a $1 billion balance sheet that is 6.45% of assets, roughly half the statutory ceiling [7]. The credit union also replaced its hard cap on individual loan size with one that rises as it grows [13].
Citadel reached $50 million by distributing it, marketing positions to other financial institutions with the assistance of Rhyze Solutions, a credit union service organization [5]. Selling participations is how individual credit unions work around the cap on large-dollar deals [4]. American Banker did not report the loan's pricing. Vincent Desimone called the deal an "elegant fit" and a "proof point" [17], and said, "By sourcing and leading the transaction, we demonstrated that we can close complex opportunities at greater scale, while retaining the local knowledge and responsiveness that differentiate Citadel" [18].
Both lenders hired the underwriting from banks. Moore joined St. Mary's in 2024 after more than 17 years at two community banks [9], and Desimone said of his own team, "We have experience that Citadel as an institution doesn't necessarily possess" [16].
On this evidence the $187.1 billion is built out of in-footprint lending, multifamily and mixed-use in St. Mary's case [19], and the Philadelphia tower is the exception that needed other lenders to close [5]. I would change that view if a second suburban credit union led a loan at Citadel's size and held it whole, or if the platform count of loans above $10 million compounds again from 16 [7].
What to watch
- NCUA's next quarterly release, and whether the commercial real estate line grows faster than credit union assets.
- Whether other financial institutions actually take up the positions marketed in the Philadelphia loan, and in what size.
- Citadel's next commercial deal: Desimone said he does not expect the Center City loan to be a one-off.